Thursday, October 22, 2015

Biocontrol making big advances

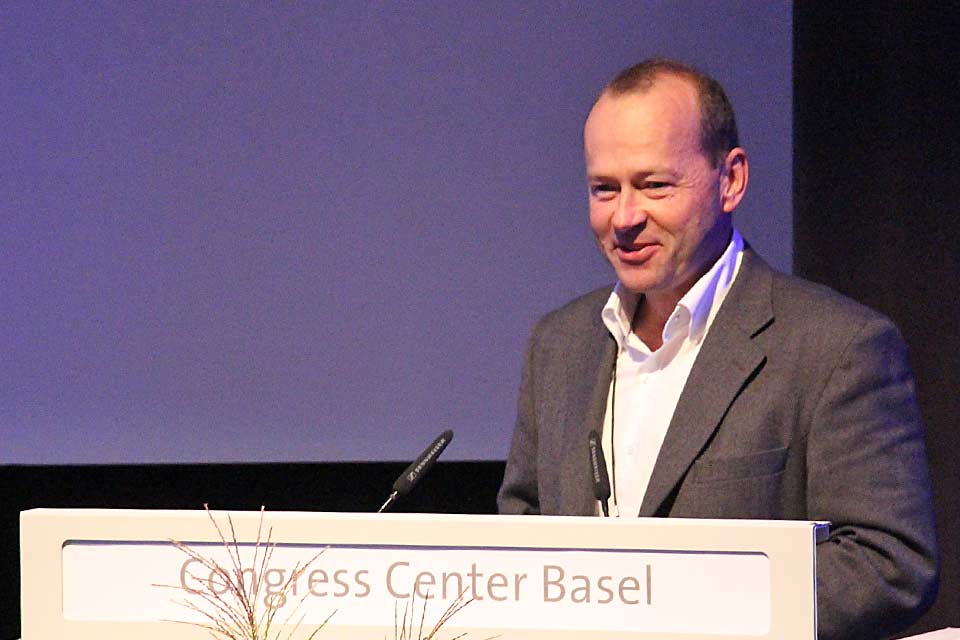
Lucius Tamm gives one of many excellent presentations at the IBMA Biocontrol conference in Basel

I have just returned from the 10th annual biocontrol conference in Basel under the auspices of the International Biocontrol Manufacturers Association. It also marked 20 years of the Association, so there was plenty to celebrate. Real progress has been made, but many challenges lie ahead.

I presented a paper on the progress made by the Association over the last decade. When I was involved in the RELU project on biopesticides, I made a number of criticisms of the lack of sophistication shown by the Association. This offended some people, but my stance was that of a critical friend. Indeed, someone stopped me in the hall and said that I had not been critical enough!

You can find the power points from my presentation here: IBMA Advocacy. This site also contains full information about our RELU project.

There were many excellent and informative papers, but I would like to just select a few points.

It is still taking far long to register new biocontrol products and make them available to farmers. The new legislative framework introduced by the European Union which is designed to facilitate their use as part of an Integrated Pest Management strategy is only slowly and imperfectly coming into effect.

In the past the typical company in the industry has been a small, often family owned company operating on a university science park. Some of these have grown into somewhat bigger but still small companies or have been taken over by medium-sized companies with an environmental portfolio. It can take so long to develop a product and get it registered and cash flow problems occur.

BASF and Bayer have now moved into the industry because they can see its growth potential with acquisitions of companies such as AgraQuest, known for its product Serenade. This has evidently caused some resentment in the industry and although the two companies are clearly on a charm offensive, I am not sure that it worked. It was also unclear to me if they really understood the specific character of the industry or had worked out their strategy in relation to it. I also think it may not generate the quick returns they might expect.

In an incisive presentation, consultant Roma Gwynn pointed out that the industry was still not reaching the vast majority of growers. Biocontrol is, as she pointed out, knowledge intensive. It does require more technical skill on the part of growers and this may not always be easy to find, as our research showed. I also think that the absence of a publicly funded agricultural advisory service is a real loss in countries such as the UK as it could help in the process of knowledge transfer.

Roma also made the point that we were living off research work done in the past. Not enough research was being done in universities and this could adversely affect innovation in the future.

An alternative report of the conference can be found here: Biocontrol

Saturday, October 17, 2015

NFU report on UK membership of the EU

The National Farmers' Union has published an evaluation of the arguments for and against UK membership of the EU from a farming perspective. At this stage they are not taking a 'better in' or 'better out' position ahead of the outcome of David Cameron's negotiations. However, this is really a holding position so that they can maximise their influence and it is difficult to believe that they would eventually recommend withdrawal.

You can read the report here: NFU Report

Agra Europe has produced an analysis of the NFU report, emphasising that it shows the way in which the CAP has become less common: An internal market?

The 'Brexit' committee I am chairing for the Farmer-Scientist Network of the Yorkshire Agricultural Society has now produced a draft first report which will be considered at a meeting in York next Friday.

How much money are dairy farmers losing?

Dairy farmers in the UK are to receive an average one off payment of about £2,000 to ease cash flow problems. A dairy farmer in England will receive an average payment of £1,820, but the figures are higher for the devolved regions apart from Wales with farmers in Scotland being paid an average £2,620. However, NFU dairy board member Rob Harrison said that farmers were, on average, £10,000 worse off in July this year than a year ago, so the average payment would not make much difference. However, there are limits to how far taxpayers can be asked to bail out businesses in trouble, even when issues of food security are involved.

Figures of losses at dairy farms often appear dramatic and one might wonder how they continue in business at all. However, they do not take account of non-dairy income and they typically are arrived after deducting a wage for every family member involved in the enterprise.

Figures from The Dairy Group cover about 150 English and Welsh herds with an average 230 cows. Milk prices ranged widely from 19p to 32p a litre with an average price of 24.7p a litre. This range is quite odd when one recalls that one is dealing with an essentially undifferentiated product, but it is a question of who the farmer's processor is. Farmers in more geographically peripheral areas often don't have a choice.

Feed costs have fallen by about 0.8p a litre, and are likely to fall further. Many milk producers will make a loss of 3p a litre this year, but this is before one takes account of non-milk income such as that from calf and cull cow sales. Non-milk income brings in about 3.6p a litre, producing a profit of about 0.8p a litre. There is also a labour charge of £20,000 per family member.

The figures do not take into account rent, tax and capital expenditure. Nor, apparently, do they include subsidies which for many farmers make the difference between a loss and a profit.

There is no doubt that dairy farmers are having a hard time. Just as in steel, a global surplus of product is driving down prices. However, there are considerable variations from farm to farm and calculating the 'profit' figure is by no means easy. Accounts are, after all, a social construction of reality.

Tuesday, October 13, 2015

Is Defra for the chop?

There are rumours that the Department of Environment, Food and Rural Affairs could be disbanded in the latest round of government cuts. It has already been severely weakened in staffing terms.

Food and farming could go to the Department of Business; environment could go to Energy and Climate Change (DECC); rural development could go to Communities and Local Government. Indeed, one could rebadge DECC as the Department of Environment, Energy and Climate Change. It is not clear who would deal with animal health and welfare.

Needless to say this hasn't gone down too well with farmers' representatives, even though some of them formed the view that Defra stood for Department for the Elimination of Farming and Rural Activity. They preferred the old clientist MAFF. But they fear that if Defra went, farming and food would not be properly represented at the Cabinet table.

Objectors say it is not clear who would lead on CAP reform, although the Treasury might like that role.

Saturday, October 10, 2015

The importance of agricultural advisory services

Historically there was a recognition of the importance of agricultural advisory services as a means of enabling farmers to improve their productivity and adopt new techniques. However, as the state has retreated from agriculture, they have suffered in some countries. The picture across Europe is now highly variable: Project on advisory services

One lesson appears that they need political support to be successful. Innovation is of key importance to farming and, of course, it can be facilitated in a variety of different ways. However, in my view, reductions in state support for applied research have not helped in countries like the UK.

Wednesday, October 07, 2015

Is French food culture under threat?

Market day in Bayonne

Not if a recent visit to Bayonne is anything to go by. On Friday evening I had an excellent meal at an not particularly pretentious restaurant. On Saturday morning, I wandered round the market where there was a wide variety of high quality goods on display from fish to vegetables. For a Brit, it was a bit of a shock to see a butcher selling horse meat.

There is an historic tradition of chocolate production in the town and I enjoyed a hot chocolate at a café, opened not so many years ago by entrepreneurs.

All may then seem to be well, but my French host thought there were a number of threats. Fast food was one, along with the traditional extended lunch going out of fashion. In the past one could go to a relatively cheap restaurant and have a decent meal with authentic ingredients prepared on the premises. There was now an increased reliance on industrialised ingredients.

Farming in the Pyrénées

Near Lescun, France

I am just back from a visit to the Pyrénées, specifically to the village of Lescun which is at a height of around 1,000 metres. Often large flocks of sheep were on the roads as 'transhumance' was taking place from the mountain areas to the valley floors. Read more about 'transhumance' here: Transhumance

The sheep here are used to produce milk from which cheese is made. This creates good value added, and along with subsidies, allows the peasants to survive. I was advised that 'paysan' is not a derogatory word in French: it is simply one of those words that does not translate well.

I also tasted yoghurt made from sheep's milk, although I preferred the product using goat milk.Reference was made to a 'progressive' local dairy farmer who had built her herd up to 20 cows. That would not be seen as viable in the UK, but it is a different style of farming.

The village

The population of the commune has shrunk as pastoralism has declined and the village has a number of second homes. Village children go to a school in the valley. Efforts have been made to ensure that there is good internet connectivity. There is a bed and breakfast (once a hotel) and some tourist activity related to the excellent opportunities for walking.

Tuesday, September 08, 2015

Aid package for farmers

Dairy farmers in particular have been hit by a global surplus of milk and the Russian embargo on EU produce. Against a background of mass protests in Brussels, the Commission unveiled a package of €500m of aid at an emergency Agriculture Council meeting: Aid package

It was important to avoid any revival of market distorting intervention measures which would be potentially expensive and could have unintended consequences, as well as exacerbating the underlying problems rather than solving them. These measures are directed primarily at farm incomes and include measures such as advancing direct payments which should ease immediate cash flow problems.

CAP expert Alan Matthews provides an in depth analysis of the measures here: Help for dairy farmers

Thursday, August 27, 2015

Hogan meets with farm ministers

EU farm commissioner Phil Hogan is holding meetings with farm ministers ahead of an 'emergency' Farm Council meeting next month to discuss the difficult situation facing EU farmers, particularly those in the dairy sector: Phil Hogan

There are calls for a restoration of full blown intervention purchases, but the active use of this policy instrument would be a step back to the past.

Monday, July 27, 2015

Demand growth for food likely to slow

Reports from the European Commission suggest that the growth in demand for food is likely to slow down due to declining population growth and more stabilisation in consumption per capita: Long-term trends

Despite slowing economic growth, China is likely to remain the main target for EU agri-food exports.

All this implies tighter export markets which are likely to restrain prices and make things more difficult for EU farmers.

Wednesday, July 01, 2015

Crop diversification measures have limited impact on farm income

The controversial crop diversification measures introduced in the last CAP reform have had a limited impact on farm income according to a new study: Crop diversification

However, individual farms may have been more substantially affected with some experiencing an income loss of as much as 10 per cent. However, it should be noted that only 38 per cent are farms are affected by the measure.

The NFU has complained about it a great deal in the UK and these figures question whether the measures are having much impact on their members. However, it may be that what was resented was what seen as an unnecessary intervention in farm level decision-making rather than any financial impacts.

Monday, June 22, 2015

The dairy farming crisis

The chairman of the NFU's south-west dairy board, Mark Oliver, has announced that he is selling his herd and quitting agriculture. He has seen the milk price he receives from his dairy fall from 33-34p a litre a year ago to 25p a litre today, with the prospect of further drops. The break even point is thought to be around 28p a litre, although this can vary by farm.

The price farmers receive does vary considerably. A number of big supermarkets such as Tesco, Sainsbury's, Marks and Spencer and Waitrose pay an agreed amount above the cost of production. This would work out at around 32p a litre. However, fewer than 15 per cent of farmers have the protection of these contracts. Typically, prices in the UK have dropped by 25 per cent over the past year, producing a price of around 20p a litre, although some farmers receive even less.

The underlying drivers are supply and demand. Global milk production is rising by 5 per cent a year while demand is growing by just 2 per cent. The average cow in England and Wales produced 14 per cent more milk in 2013 than a decade earlier.

China's economic slowdown has reduced its demand while Russia imposed a ban on EU dairy products last year. The two countries account for not far short of a third of globally traded dairy products, so have had a significant impact on prices.

Chinese imports have jumped 14 times in the last decade. This is, of course, from a low base with milk and cheese being relatively new to the diet.

The number of dairy farmers in England and Wales has dropped by half over the past 12 years to just under 10,000. However, this means that the remaining farmers have better economies of scale, are generally more efficient and better able to compete internationally.

It's not all doom and gloom in the long run. The International Farm Comparison Network reckons that the world will need 30 per cent more milk by 2024. The demand would come from population growth and per capita dairy consumption rising by 14 per cent.

The Middle East and North Africa have seen rapid expansion of their dairy markets. While world trade of dairy products has doubled in the last decade, Middle Eastern imports have trebled and Maghreb countries have seen a 3.5 times rise. One of the main attractions of the region is the scope for processed dairy products such as cheese. In Asia the market has been mainly focused on milk and powdered milk.

Wednesday, April 08, 2015

What would British withdrawal from the EU imply for British farm policy?

Farmers are uncertain what impact a British exit from the European Union would have on their businesses. This is not surprising as so far there has been little systematic exploration of these issues, says the Farmer-Scientist Network which has been set up by the Yorkshire Agricultural Society.

The Farmer-Scientist Network is based at the Great Yorkshire Showground, and has assembled a working party of CAP experts from economics, law and political science chaired by Professor Wyn Grant of Warwick University. North Yorkshire farmer, Bill Cowling, who is best known as the Honorary Show Director of the Great Yorkshire Show, is a working party member and is helping to identify the issues that concern farmers in particular.

He comments: “The impact of a possible withdrawal from the EU cannot be under estimated. The Yorkshire Agricultural Society was established to drive forward developments in farming, and it is anticipated that this Network will encourage a more informed debate in the event of a referendum.”

The Network has raised the point that Britain would be outside the Common Agricultural Policy (CAP) and would have to devise its own agricultural policy. The shape of that policy would, however, be influenced by the form that the relationship with the EU took after exit and obligations under the international trade regime as Britain would remain a member of the World Trade Organisation.

Over the next few months the working party will examine:

  • Financial support for farmers post exit
  • The tariff regime that would be followed outside the EU
  • What would happen to environmental regulations
  • The availability of migrant labour

Friday, April 03, 2015

The productivity puzzle

Britain's recent poor productivity performance, which necessarily has an effect on real wages, is the issue that dares not speak its name in the general election. It doesn't reflect well on the Coalition Government, but Labour has not pushed the issue, perhaps because they have no answers.

Britain's record in agricultural productivity has been poor. Between 1900 and 1984, yields of wheat trebled from one tonne to three tonnes an acre. Since then, although there was some improvement in the late 1990s, productivity has more or less flat lined.

Using USDA and OECD data, England ranks seventh out of eight countries on ratio of farm outputs to inputs by value (excluding subsidies). The World Bank calculates that the country produces less cereal per hectare of harvested and than Belgium, France, Germany or the Netherlands.

To put it another way, if we start with a 1990 index of 100, Britain's agricultural productivity was around 118 in 2011. The US was on over 140, the Netherlands and Germany in the 170s, New Zealand near 220 and Denmark over 220.

The high price of agricultural land in Britain doesn't help. It's a popular, lightly taxed investment asset, also popular for sporting and lifestyle purposes. Its steep rise in value absorbs funds that might otherwise be used for investment.

There has also been a sharp fall in applied research and development with a number of public research institutes wound up in the 1980s. Over the past two decades the country's spending on agricultural R & D has fallen by an average of 6 per cent in real terms.

The UK did launch an agri-tech strategy in 2013 with cross-party support, but it is open to question whether the £160m allocated to it is enough or whether it has come too late.

Monday, March 23, 2015

Balls in less farm subsidies shock

There was what I found to be a rather surprising exchange on agricultural policy at the end of the questioning of Ed Balls as Shadow Chancellor on Sky this afternoon. Someone from the farming industry asked him about declining self-sufficiency in UK agriculture, no doubt him expecting to say that targets to increase it should be set. The NFU has just tweeted that she is one of their members.

Instead he said that he believed in international trade and that this gave consumers a wider choice of products in the supermarkets and this kept prices down for consumers. He was also critical of the CAP, although that is standard for UK politicians.

He was then asked by the facilitator whether he favoured more farm subsidies or less and he unequivocally answered, 'Less'.

Monday, March 16, 2015

Campaigning for farming and food in the general election

The general election is an opportunity for farming and food issues to be debated and the National Farmers' Union is fully entitled to brief its members with questions to be asked of candidates. Indeed, the NFU has posed very interesting questions about any referendum on membership of the EU and what the implications of 'Brexit' might be for British agriculture, an issue that requires more systematic attention and exploration.

What I think is less helpful is any suggestion that we need self-sufficiency targets which can all too easily smack of Soviet central planning. The NFU has warned that by 2080 less than half the nation's food needs will be met by UK farming. This date is a long way away and it is not clear whether this is a figure for temperate foodstuffs or whether it includes tropical products like the ever popular banana.

The NFU's report entitled Backing British Farming in a Volatile World said that 85 per cent of consumers wanted to see supermarkets selling food from British farms. This is a bit like asking people whether they are in favour of motherhood and apple pie.

There are food security issues to be discussed, but as Tim Benton of Leeds University, the UK's global food security champion, commented: 'It remains an "open question" as to what the optimal level of self-sufficiency should be.' I would argue that there is no methodology that can tell us, given all the uncertainties. That may, of course, represent a case for being cautious, but I don't think that target figures are the right way forward.

The NFU claims that more than half the income of an 'average' farm comes from single farm payments (soon to be the basic payment). This suggests an over dependence on subsidy, but the NFU says they are needed to protect against price volatility. What would perhaps help more is a supermarkets ombudsman with more powers and a staff of more than three to ensure more of a level playing field. But then governments like low food prices.

You can read the NFU report here: Backing British Farming

Friday, March 13, 2015

Mid-term review on the cards?

Many observers of the CAP, particularly environmentalists, were disappointed with the last reform of the CAP. They argued that it was not a reform at all, which has been true of many so-called reforms of the CAP, honourable exceptions being those initiated by Commissioners MacSharry and Fischler.

Commissioner Hogan has responded to the criticisms, saying that there could be a mid-term review of the CAP in 2017, leading to more reforms: Mid-term review?

Some scepticism is in order, as a mid-term review may lead to little more than some tweaking and cosmetic changes. However, at least it shows that the possibility of a renewed reform debate is not dead.

Wednesday, March 11, 2015

Huge growth in price of best arable land

The average price of UK farmland reached a record of just over £10,000 an acre in the second half of 2014. This is 8.3 per cent up on the previous year and the 11th year in a row that prices have broken the previous record. However, the average price masks a growing gap between the price of top quality arable land and ordinary pasture.

The price of prime arable land, mainly in East Anglia, rose by 277 per cent in the decade to 2014 according to figures from Savills. These figures beat prime London property, up 127 per cent over the last decade, the FTSE All-Share index and even gold. Rumners Farm, a 560-acre North Cambridgeshire arable estate sold for about £2.75m in 2007. Now it is back on the market at £8m.

Investors are pushing up the price of the best land. Bagless vacuum cleaner magnate Sir James Dyson has been buying up land in Lincolnshire. He now has 25,000 acres, having recently purchased the 3,000 acre Cranwell and Roxholme estate. According to Mark McAndrew of Strutt & Parker private investment competition can push up the price from £7,000 an acre to £12,000-£13,000.

Investors are interested in land as a counter-cyclical safe asset. With a growing world population, food prices should rise in the long term.

Other hotspots include Hampshire, Berkshire and Oxfordshire, 'Home Counties' that are within easy reach of London and appeal to lifestyle buyers who may want to breed horses.

What is curiously missing from the reports I have read is any mention of the CAP. The subsidies it provides make land a more attractive asset and push up prices. It then becomes difficult for new entrants unless they inherit, become farm managers or are prepared to start with a marginal livestock enterprise. The sector may be deprived of innovative new talent.

Rising land prices do nothing for the 30 per cent of farmers who are tenants. For dairy farmers under the cosh from falling prices for their milk they offer the prospect of a better return if they sell up as many are doing. However, their farms are rarely in the most lucrative areas.

Saturday, March 07, 2015

Complex picture on cutting payments to big farms

A common complaint about the CAP is that too high proportion of the subsidies go to already prosperous farmers. The counter argument is that these farmers are the most efficient and the most internationally competitive. It all comes down to what you think the CAP is for and there has always been confusion about the objectives and their relative preference ordering.

From this year all member states are obliged to apply a 5 per cent degressivity tax on payments over €150,000. Let us suppose that you are an East Anglian grain baron receiving €1m in subsidies. This means that you would appear to lose €42,500 of your subsidy, but then the 30 per cent greening subsidy is exempt, so the actual sum comes in at under €30,000 (obviously the amount received in pounds is sensitive to the pound-euro exchange rate). The amount lost would be significant but not devastating.

However, any member state or region can impose their own cap. This option has been chosen by all the devolved regions in the UK, but on a different basis in each case: It's your choice

Northern Ireland has imposed an absolute cap at €150,000. There are not many farms in Northern Ireland who would receive more than this. Wales has come up with a particularly complicated system, but again there are not that many farms in Wales who would qualify for relatively large payments. Scotland, where there are some large farms, has set the cap higher. Indeed, their €600,000 starting point is the highest notified by any EU country or region.

It's not difficult to work out the politics of this. Farmers in Northern Ireland who are Democratic Unionist or Sinn Fein supporters are unlikely to be affected. In Wales, the more Welsh-speaking parts of the country are unlikely to be hit (although other aspects of Welsh Assembly Government policy have been a source of complaint). In Scotland, the Scottish Nationalists do not want to upset any constituency, but the relatively small number of farmers likely to be affected are not significant in electoral terms.

Thursday, January 15, 2015

The future of small farms

The president of the Agricultural Economics Society, Steve Wiggins, has written some interesting reflections on this enduring topic in their latest newsletter which I reproduce below.

'Small-scale family farms remain an enduring feature of agriculture across the world, and especially so in the developing world. Some 418 million farms in the developing world, 95%, have less than five hectares, according to broad estimates made by FAO from (inadequate) surveys and censuses. What's more, in most developing countries the average holding size still tends to fall with each decadal census.

Debates over the productivity of small farms and their likely evolution go back to the nineteenth century if not before. The end of the peasantry has been repeatedly announced, yet reality has proved otherwise. Concerns that smallholdings could not be efficient and would never allow sufficient increases in production to sustain development were voiced in the 1950s and early 1960s; but laid to rest when the green revolution showed what could be achieved on the small farms of Asia. Analyses confirmed that many smallholders ran efficient farms and responded to price incentives. Indeed, diseconomies of scale were apparent, since small farms could manage labour better than larger scale farms.

But like Malthusian pessimism, doubts about small farms periodically resurface. The latest bout began around the turn of the new century, inspired by observations of the new supply chains run by supermarkets and exporters springing up across the developing world. Small farmers would be at a definitive disadvantage in these chains, since they could not meet the exacting demands for standard, high quality production, to strict timetables, in large lots and preferably certified and traceable.

Contemporary Asia, where only a small fraction of farms exceed five hectares, provides some insights into changes and likely future trajectories. Even in rural areas well connected to cities, where supply chains are modernising for staples and not just high-value produce, family farms persist. These farms are, however, increasingly differentiated, as a minority specialise in farming and intensify their production; while most farms provide some income for rural households that increasingly rely on non-farm activities and remittances from migrants.

This throws up two challenges. One, land markets need the flexibility to permit some concentration of holdings in larger operating units, while rural households that want to retain ownership, but lack the means or inclination to cultivate, can do so. At issue are small-scale transfers, perhaps temporary arrangements, with rentals, share-crops and loans predominating over outright sale. Tenure policy needs to facilitate these exchanges.

Two, if small farms are to prosper they need to find ways to overcome the failures that typically apply in markets for inputs and credit. That can be done, of course by the state, but the costs can be (ruinously) high. The alternative is to look to private and collective institutional innovations - contracting, farmer associations, local agencies and franchises for inputs and finance, etc. - to overcome current market shortcomings. A plethora of such initiatives can be seen, even if most operate at limited scale. The challenge then is to learn from these, to find working models - not pilots - that can be replicated or adapted to wider circumstances.

Get these two things right and we can hope to see a gentle transition as most smallholders gradually leave farming on their own terms, while allowing specialising smallholders to expand their holdings.'

One might add that many family farms in countries like the US and the UK have become successful large-scale enterprises but that was dependent on a number of factors including: (i) a facilitating legal framework on inheritance; (ii) good infrastructure to get products cheaply and quickly to markets; (iii) mechanisms to learn about and adopt technological innovations; (iv) ready availability of credit at realistic rates; (v) some government financial support for modernisation. No doubt one could add to this list.